05
Oct
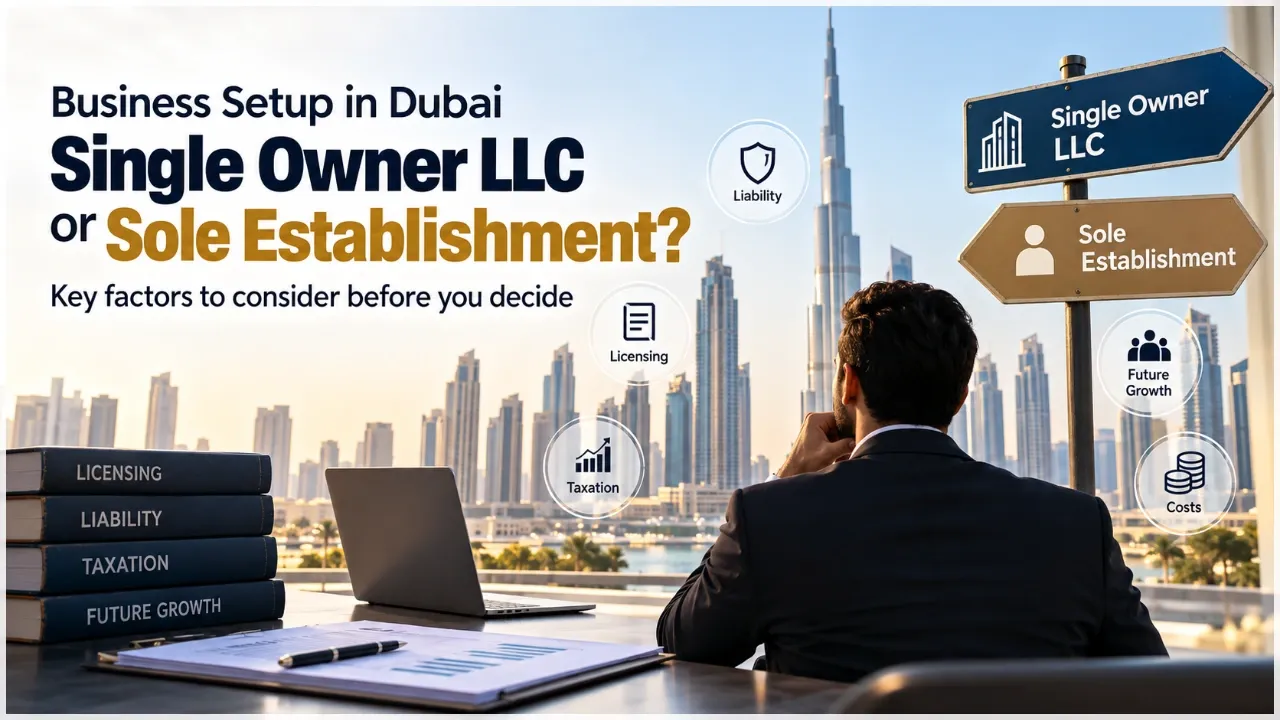
Single-Owner LLC or Sole Establishment in Dubai: A Founder's Decision Guide
A solo founder can have more than one possible business structure in Dubai. Choosing between an eligible single-owner LLC and a sole establishment requires more than comparing licence prices. Consider how the activity is permitted, who carries liability and whether the business will need partners or investment later.
Start with eligibility and legal personality
Ask the licensing authority which legal forms are available for the exact activity and owner profile. A company and a business carried on by an individual are not interchangeable structures. An LLC generally separates the company's legal personality from its owner, but contractual guarantees and particular legal obligations can still create personal exposure. Have the actual documents reviewed before relying on a shorthand description of limited liability. Official reference.
Compare the tax position correctly
The FTA distinguishes juridical persons from natural persons for corporate tax purposes. Do not apply an individual's business turnover test to an incorporated company. Equally, do not assume an individual business is treated like a company simply because it holds a licence. Review the legal form, relevant income and registration obligations together, then establish an accounting approach that reflects that assessment. Official reference.
Plan for the second stage
Think about customer procurement requirements, hiring, borrowing and bringing in another owner. A structure suitable for a small personal service may need changes when the founder takes on larger contractual exposure. Ask what adding a shareholder or changing the form would involve. Document founder funding and withdrawals from the beginning so growth does not depend on reconstructing personal transactions later. Official reference.
Compare a claim and a funding event
Use two hypothetical events when discussing the structure with a legal adviser: a customer makes a substantial claim, and the founder needs outside funding. Ask which assets and obligations sit with the entity, what a personal guarantee would change and how a new owner or lender can participate. These examples make the implications easier to understand than a general statement that one form offers better protection. They also reveal whether the chosen structure suits the contracts the founder actually expects to sign.
Check the cost of changing direction
Request a written explanation of the process if the business later changes legal form, introduces a shareholder or transfers key contracts. Include document amendments, authority approvals, bank review and any customer consent. The future change may be entirely workable, but it should be a conscious assumption in the launch plan. Keep the initial operating records clear so a later restructuring can distinguish company assets, founder funding, customer balances and personal transactions without months of reconstruction.
Keep a clear evidence register
An evidence register should link each important decision to the document supporting it. Retain the authority's legal-form confirmation, signed formation documents, customer requirements and the tax classification advice. Include the issuing party, the document date and the current version.
Track the number that affects cash
Select a measure that explains how the operation turns work into cash. Track the expected contractual exposure and funding needs against the benefit of the selected legal structure. Use a consistent definition so monthly comparisons are meaningful. Investigate exceptions rather than relying only on a total, and discuss the result with the person responsible for delivery.
Put approvals ahead of dependent commitments
List which commitments depend on another task being completed. Confirm activity eligibility, review liability and tax status, then select the structure before signing long-term customer commitments. Show these links in the plan and keep them visible when the launch date changes. Ask providers what evidence marks completion of their stage and retain it. Where a permission remains uncertain, favour a reversible commitment until the condition is resolved. This keeps commercial momentum while reducing the chance that the company pays for an operating resource it cannot yet use.
Write down the allocation of responsibility
Clear responsibility is especially valuable when several parties deliver one customer outcome. Check who is the contracting party and whether any customer requests a personal guarantee from the founder. Identify who owns the promise, who provides the work and who handles a failure or refund. Explain the charges and the conditions for approving additional work. The signed agreement should align with the quotation and delivery process. If those documents disagree, settle the difference before the transaction begins instead of leaving the customer and staff to infer what the business meant.
Close the loop on operating records
A control is useful only when an exception leads to a correction. Record money introduced by the owner and withdrawals under the classifications appropriate to the chosen legal form. Record the check, the discrepancy and the action, then verify that the action was completed. Repeated errors may indicate a process problem rather than careless staff. Review the source document before changing an accounting entry, and preserve the explanation for any adjustment.
Give advisers the facts that matter
A short factual brief helps an adviser resolve the right issue. Ask how this structure handles an additional owner, a customer claim and the first corporate tax registration assessment. Include what is already approved and what remains proposed. Distinguish a legal requirement from a commercial concern, such as customer acceptance or a supplier condition. Ask for the documents or authority confirmation needed before the next commitment. Keep the response with the decision it informed. The result is a usable record of why the founder selected a particular route and which assumptions still need checking.
Define the provider handover
Include the handover in the professional scope before work begins. Ask what issued documents, application references, portal permissions and renewal information the company will receive. Identify any task excluded from the fee and the person who will complete it. Keep authority receipts separate from the provider invoice, and reconcile both against the original quote. A clear handover avoids uncertainty when the founder needs to make an amendment or answer a question months after the setup project has ended.
Keep responsibilities visible
Document who can approve expenditure, sign a customer commitment, submit company information and view sensitive records. Review this list when staff or shareholders change. Essential accounts should have an appropriate recovery route and more than one authorised person where the system allows it. Retain documents in a company-controlled location rather than relying on a personal inbox.
Check the first deliverable before opening
Before the first delivery, run a short check using the actual customer requirement. Confirm that the people, systems, evidence and permissions needed for that deliverable are available. Identify any missing item and decide whether it stops the work or can be resolved afterwards. Keep the decision specific and assign a responsible person. This approach turns a broad opening checklist into a practical assessment of the company's ability to fulfil its first commercial promise.
Reassess after the initial cycle
Once the first delivery and collection cycle is complete, compare the actual operation with the setup assumptions. Look for changes in customer profile, geography, staffing, suppliers and service scope. Check whether these changes affect any permission, agreement or financial process. Use the result to revise the next-stage budget and request professional advice where necessary. An early review helps the company learn from real transactions before it repeats an unsuitable arrangement across a larger customer base.
Official sources and further reading
- Invest in Dubai: business setup and licensing
- Federal Tax Authority: corporate tax FAQs
- Federal Tax Authority: corporate tax registration
Research checked on 2 October 2026. Confirm the current activity requirements, fees and approvals before applying.
For help with choosing a suitable company structure, explore company formation support or contact Right Time with your planned activity and launch date.
Frequently Asked Questions
Is the cheapest legal form always best for a solo founder?
No. Compare eligibility, liability, tax classification and future ownership needs.
Can every activity use either structure?
Availability depends on the activity and licensing rules. Obtain confirmation for the specific application.
Choose a Structure That Fits Your Plan
Explain your activity, ownership and expected customer contracts to Right Time before selecting a legal form.
Talk to Right Time