23
Oct
Dubai Online Retail Setup: Choose Your Stock and Import Model Before Licensing
An online retailer's website is only one part of its business model. The company may own local stock, import goods, use a marketplace warehouse or arrange supplier fulfilment. Decide which model applies before choosing activities and signing supplier contracts in Dubai.
Identify the seller and importer
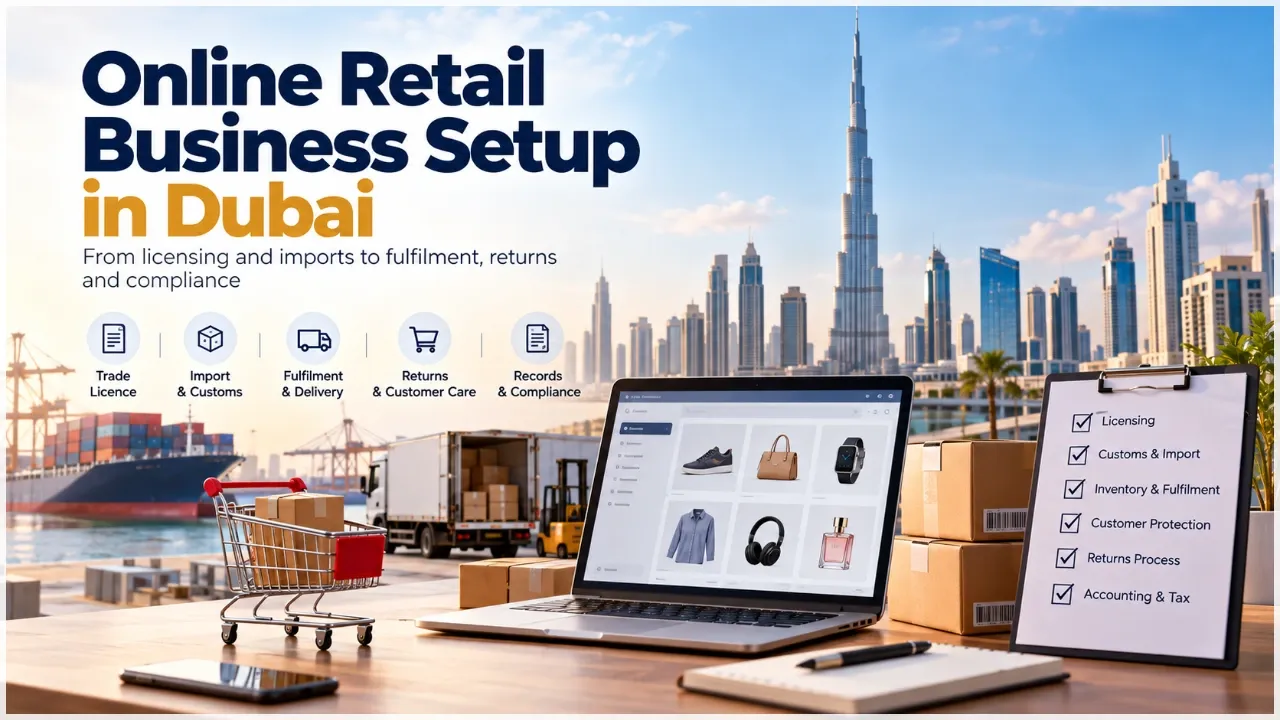
Write down which entity sells to the customer, owns the inventory and acts as importer where goods cross the border. Confirm the licence scope and required customs registration for the arrangement. A marketplace account does not automatically replace the retailer's obligations. Product-specific requirements must also be assessed; a broad trading description is not proof that every category can be offered without further approval. Official reference.
Prepare customer and fulfilment terms
State delivery expectations, returns, warranty responsibilities and customer support clearly. Check the applicable UAE consumer requirements with a qualified adviser where necessary. Agree how a fulfilment provider records dispatch, damaged goods and returns. If the supplier ships directly, document who bears delivery failure and import responsibilities. The customer should be able to identify the seller and understand the actual service promise. Official reference.
Build records around the order
Use an order identifier that connects the sale, tax treatment, inventory movement, platform fees and settlement. Separate gross customer payments from amounts received after deductions. Record returned goods and refunds in the proper period. Early reconciliation reveals whether the product margin survives fulfilment, advertising and returns, instead of hiding losses behind a growing marketplace sales total. Official reference.
Map a return before launching sales
Follow a hypothetical return from the customer's request through approval, collection, warehouse receipt, refund and stock classification. Decide who pays each cost and what evidence confirms the item is eligible for resale. Check the process against applicable customer rights and the agreements with fulfilment providers. A return policy is useful only if the operational team can carry it out. Testing it early exposes missing responsibility or information before dissatisfied customers and unreconciled inventory accumulate.
Avoid confusing a fulfilment location with an operating licence
A warehouse may store and dispatch stock while your company remains the seller. Record that distinction and verify the provider's role and approved services. If the business later adds its own collection point, showroom or service premises, assess the local permission requirements before opening. The fact that an online business can take an order through a website does not resolve every physical activity associated with that order. Review the entire transaction rather than treating the sales channel as the complete business model.
Keep a clear evidence register
An evidence register should link each important decision to the document supporting it. Retain supplier invoices, import records, product permissions, customer orders, dispatch evidence and marketplace settlement statements. Include the issuing party, the document date and the current version.
Track the number that affects cash
Select a measure that explains how the operation turns work into cash. Measure contribution per kept order after fulfilment, advertising, commission and the cost of expected returns. Use a consistent definition so monthly comparisons are meaningful. Investigate exceptions rather than relying only on a total, and discuss the result with the person responsible for delivery. Set a threshold for management review when the number deteriorates. Good measures support a decision about capacity, pricing, credit or purchasing; they are not simply a way to make a launch report look impressive.
Put approvals ahead of dependent commitments
List which commitments depend on another task being completed. Confirm seller and importer roles, check product requirements, complete registration and test order-to-settlement records before buying larger stock. Show these links in the plan and keep them visible when the launch date changes. Ask providers what evidence marks completion of their stage and retain it. Where a permission remains uncertain, favour a reversible commitment until the condition is resolved. This keeps commercial momentum while reducing the chance that the company pays for an operating resource it cannot yet use.
Write down the allocation of responsibility
Clear responsibility is especially valuable when several parties deliver one customer outcome. Define title to goods, delivery, returns, warranties, import responsibilities and the fulfilment provider's handling of damaged stock. Identify who owns the promise, who provides the work and who handles a failure or refund. Explain the charges and the conditions for approving additional work.
Close the loop on operating records
A control is useful only when an exception leads to a correction. Reconcile orders, inventory movements, refunds, marketplace deductions and bank settlements without netting away unexplained differences. Record the check, the discrepancy and the action, then verify that the action was completed. Repeated errors may indicate a process problem rather than careless staff. Review the source document before changing an accounting entry, and preserve the explanation for any adjustment. This routine gives the founder better information during the launch and makes the eventual financial reporting more dependable.
Give advisers the facts that matter
A short factual brief helps an adviser resolve the right issue. Ask which activities and registrations cover your exact stock location, import route, product category and customer delivery model. Include what is already approved and what remains proposed. Distinguish a legal requirement from a commercial concern, such as customer acceptance or a supplier condition. Ask for the documents or authority confirmation needed before the next commitment. Keep the response with the decision it informed. The result is a usable record of why the founder selected a particular route and which assumptions still need checking.
Define the provider handover
Include the handover in the professional scope before work begins. Ask what issued documents, application references, portal permissions and renewal information the company will receive. Identify any task excluded from the fee and the person who will complete it. Keep authority receipts separate from the provider invoice, and reconcile both against the original quote. A clear handover avoids uncertainty when the founder needs to make an amendment or answer a question months after the setup project has ended.
Keep responsibilities visible
Document who can approve expenditure, sign a customer commitment, submit company information and view sensitive records. Review this list when staff or shareholders change. Essential accounts should have an appropriate recovery route and more than one authorised person where the system allows it. Retain documents in a company-controlled location rather than relying on a personal inbox.
Check the first deliverable before opening
Before the first delivery, run a short check using the actual customer requirement. Confirm that the people, systems, evidence and permissions needed for that deliverable are available. Identify any missing item and decide whether it stops the work or can be resolved afterwards. Keep the decision specific and assign a responsible person. This approach turns a broad opening checklist into a practical assessment of the company's ability to fulfil its first commercial promise.
Reassess after the initial cycle
Once the first delivery and collection cycle is complete, compare the actual operation with the setup assumptions. Look for changes in customer profile, geography, staffing, suppliers and service scope. Check whether these changes affect any permission, agreement or financial process. Use the result to revise the next-stage budget and request professional advice where necessary. An early review helps the company learn from real transactions before it repeats an unsuitable arrangement across a larger customer base.
Official sources and further reading
- Dubai Customs: business registration and customs code
- Ministry of Economy and Tourism: consumer protection law
- Invest in Dubai: business setup and licensing
Research checked on 2 October 2026. Confirm the current activity requirements, fees and approvals before applying.
For help with structuring an online retail company, explore trade licence support or contact Right Time with your planned activity and launch date.
Frequently Asked Questions
Does marketplace approval replace a trade licence?
No. Assess the seller's licensing and product obligations independently.
Should refunds be tracked separately?
Yes. Link them to the order, stock movement and settlement so sales and margin remain understandable.
Plan the Retail Model Before Buying Stock
Share your products, supplier location and fulfilment plan with Right Time to organise the licensing and registration review.
Talk to Right Time